


The U.S. power grid is experiencing a change unlike anything seen in the past. Artificial Intelligence (AI) is driving the development of massive data centers that require incredible amounts of electricity, and many of these facilities are being planned and constructed much faster than the generation and transmission infrastructure required to support them.
Some of the largest technology companies have already realized the challenge. Microsoft signed a 20-year agreement supporting the restart of the former Three-Mile Island nuclear plant, now known as the Crane Energy Center, while Meta entered into a 20-year agreement to continue operations of the Clinton Clean Energy Center in Illinois. Meta’s agreement also supports a 30 MW increase at the facility. These deals are not the same as the emerging regulatory concept of “Bring Your Own Capacity,” but they show the broader trend of large electricity users getting more involved in securing the generation needed for them to grow.
That pivot raises an important question for electricity markets. If a new data center creates the need for thousands of MWs of new generation and transmission investment, how much of that responsibility should be put upon the customer creating the need and, more importantly, how much of that added responsibility should be socialized with end users already connected to the grid?
The Grid Was Not Designed for This Type of Growth
In the past, a large commercial or industrial end user could connect to the bulk electric system and rely on the utility, regional grid operator and wholesale competitive market to ensure sufficient power was available.
The scale and pace of today’s development are changing that model.
Data centers typically take 18 to 36 months to move from development to operation. New power plants generally take longer, and new transmission infrastructure can take much longer. Looking at MISO as an example, estimates show that large loads may seek to connect within one and a half to three years, compared with about four years for new generation and closer to 10 years for major transmission projects.
The issue is kind of straightforward. A grid cannot reliably add several gigawatts of demand if the infrastructure producing and moving those gigawatts is not keeping pace.
This creates three interconnected challenges:
- Reliability: Is there enough generation available to serve the new load when it arrives?
- Infrastructure: Can the transmission system physically deliver that power where it is needed?
- Cost: Who ultimately pays for the generation, transmission and other grid upgrades required to serve these new loads?
Making those decisions is made more difficult by speculative, or "phantom" load. Data center developers may evaluate multiple sites at the same time before selecting where a project will actually be built. If every request is incorporated into long-term planning, utilities and grid operators risk planning billions of dollars in infrastructure around projects that may never some to be. On the other hand, waiting too long to plan for legitimate projects could leave the grid unprepared when that demand does arrive.
These concerns have now reached the federal level. In June 2026, FERC opened separate proceedings covering all six regional grid operators under its jurisdiction, including PJM, MISO, SPP, NYISO, ISO-NE and CAISO. ERCOT is not subject to FERC jurisdiction in the same way. Among the many issues being looked at are more robust transmission service and study processes, cost-shifting protections, co-located generation, flexible load arrangements and improved processes for studying generation located close to new large loads.
There is not really one true solution here. Each market has different resource mixes, planning structures and reliability challenges, and the regional approaches are likely to vary.
What Does Bring Your Own Capacity Mean?
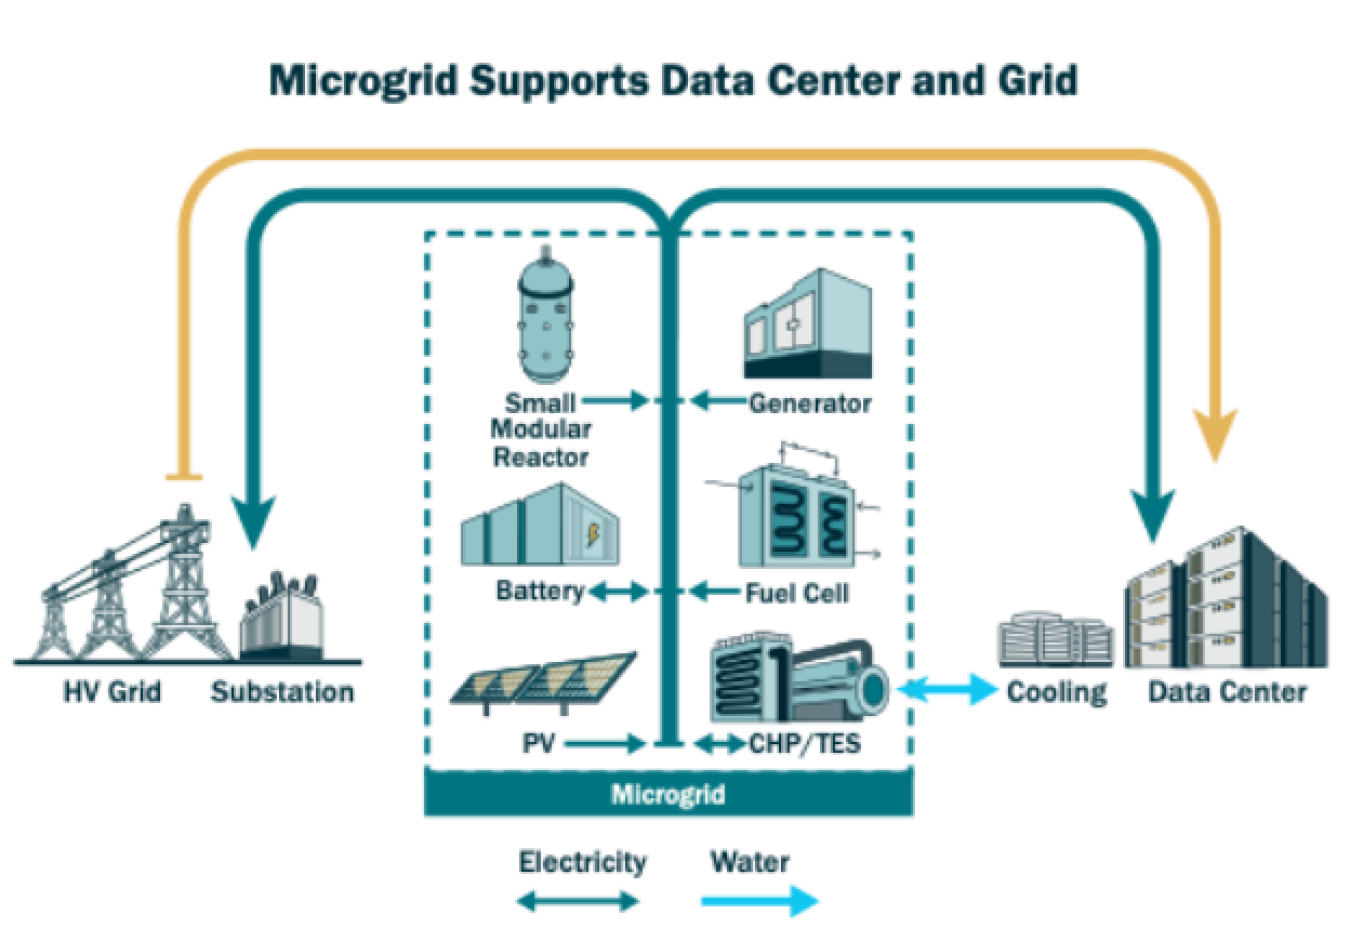
Bring Your Own Capacity (BYOC) is a simple concept with some complicated implementation.
 Source: Energy.gov
Rather than connecting a new large load and assuming the larger grid will eventually have the necessary generation to serve it, the customer brings, contracts for, or otherwise supports enough incremental capacity to cover some or all of its new demand.
That could include new generation developed specifically for the new large load, a long-term agreement that supports incremental generation, co-located or behind-the-meter resources, energy storage, or arrangements allowing that user to curtail consumption when the grid is stressed. The exact definition and qualifying resources will ultimately depend on the rules of each market.
There is also a very important distinction that needs to be made. A 50 MW data center cannot necessarily solve its burden on the system by building a 50 MW nameplate generator.
Grid operators are concerned with accredited or qualifying capacity, meaning how much of a resource can reliably be counted on when the system needs it. A 50 MW resource may therefore contribute considerably less than 50 MW toward a customer’s capacity requirement depending on the technology and capacity accreditation rules applied to that market.
That difference will become very important as large users assess combinations of natural gas, nuclear, renewables, storage and demand flexibility.
PJM is Moving Quickly
No U.S. market illustrates this issue better than PJM.
Data center development has added to rapidly growing load forecasts and at the same time the region is having a hard time adding new generation quickly enough. PJM’s most recent capacity auction cleared 6,831 MW short of its reliability requirement, reinforcing the adjustments being made by PJM to accelerate new supply and maintain reliability.
The most significant of these adjustments is the proposed Reliability Backstop Procurement auction.
This auction is effectively designed to help close the reliability gap. PJM would seek commitments from new generation resources for terms extending as far as 15 years. Eligible projects would generally be required to provide new capacity and be capable of coming online no later than June 1, 2032.
The long-term contract is essential because one of the barriers to new generation is financing. A project developer may be hesitant to invest billions of dollars in a power plant based solely on capacity prices that change from auction to auction, even if recent prices have been elevated. Those elevated prices have not been enough to spur significant new builds. A longer-term commitment gives the developer a more predictable revenue stream against which a project can potentially be financed.
Under PJM’s proposal, developers would submit offers in dollars per MW-day of accredited capacity. The procurement would be pay-as-bid, and PJM would select qualifying projects based on timing and cost. PJM has proposed a maximum volume-weighted average willingness to pay of $555/MW-day.
Selected resources would then participate in PJM’s normal base residual auctions as price takers, offering in at $0/MW-day. The Reliability Backstop Procurement auction would then serve as a contract-for-difference between the project’s accepted backstop price and its applicable capacity market clearing price.
For example, assume a project receives a reliability backstop commitment of $500/MW-day and a future base residual auction clears at $300/MW-day. The project would receive the base residual auction rate, plus an additional $200/MW-day covering the difference between the reliability backstop price and the normal capacity price. The objective is not to automatically pay every project the maximum, but to provide select resources with long-term revenue to bring new capacity onto the system.
Who ultimately pays is especially important for existing customers. PJM proposes allocating reliability backstop costs initially based on load growth forecasts by zone, with states and electric distributors playing a major role in determining how those costs reach individual customers. PJM itself acknowledges that if states do not establish mechanisms to assign costs appropriately to large loads, some of those costs could be allocated more broadly using existing capacity obligations.
That is why the large-load debate matters to end users that have nothing to do with data centers.
What Happens if a Data Center Doesn’t Bring Capacity?
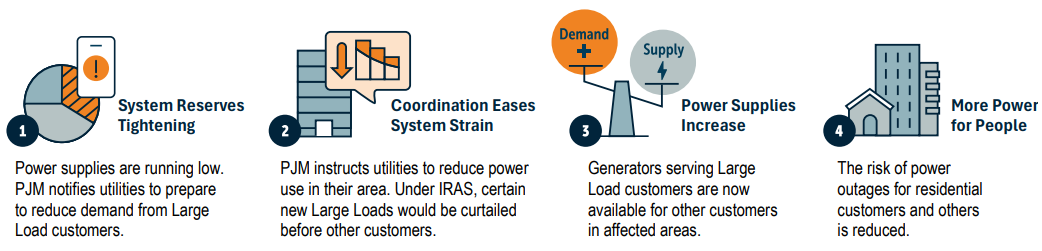
PJM’s second significant proposal is Interim Resource Adequacy Service, or IRAS.
 Source: PJM
Rather than disallowing a new data center from connecting because sufficient capacity has not been added yet, IRAS would potentially allow the facility to connect while accepting a different type of reliability agreement.
Under IRAS, new large loads of 50 MW or more would be tracked through a large-load registry. Loads that do not bring adequate new capacity and are not supported by the reliability backstop auction would be required to reduce consumption or switch to on-site backup generation during high-demand periods. Those curtailments could occur prior to any deeper moves into PJM’s emergency load-management actions that impact the broader grid.
In simple terms, PJM is trying to establish more than one path.
Bring enough new capacity and operate normally. Receive capacity support through the reliability backstop. Or accept curtailment risk under IRAS.
That represents a meaningful departure from the historical assumption that every new customer can simply connect and expect the broader system to serve it under all operating conditions.
How Other Markets Are Responding
PJM may be moving the quickest, but the same issue is showing up across the country. Each market is approaching it a little differently based on its own generation mix, planning structure and reliability challenges.
-
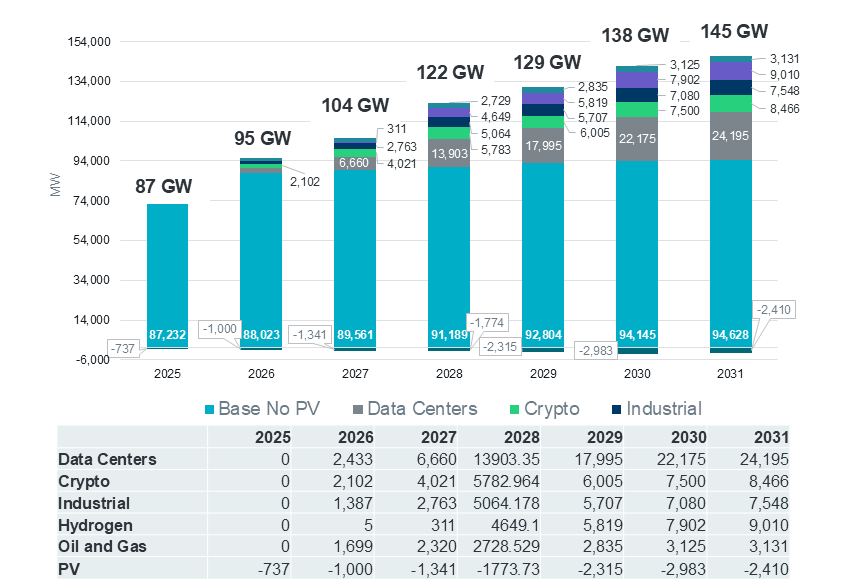
ERCOT is facing the problem at Texas scale. As of April 2026, ERCOT was tracking about 410 GW of large loads seeking interconnection, roughly 87% of which were associated with data centers. Not all these projects will see the light of day, which makes determining what is real and what is not a major planning challenge. ERCOT is moving toward a batch process for looking at large-load connections while also exploring how flexible demand can support grid reliability.
 Source: ERCOT
-
MISO is focused heavily on the timing issue. Large loads are looking to connect within roughly 18 to 36 months, while the generation and transmission needed to support them can take much longer. MISO is looking at ways to better coordinate large-load additions with new generation, including studying them concurrently and potentially allowing faster access through non-firm transmission service.
-
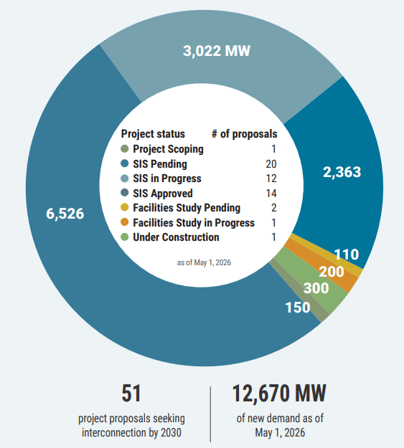
NYISO is looking closely at cost protection and flexibility as New York deals with its own tightening reliability outlook. Among the issues being considered are new transmission-service options for flexible large loads, protections against shifting network-upgrade costs to existing customers and ways to increase the speed at which new generation can be added.
Source: NYISO
- ISO-NE has not yet experienced data center development at the same scale as some other regions, giving New England a little more time. The ISO is coordinating with transmission owners on potential large-load interconnections and participating in FERC’s broader review. Massachusetts, however, recently took a more direct approach. Governor Healey signed an executive order requiring new or expanding data centers with peak demand above 25 MW to procure enough new clean energy to offset their annual consumption or potentially make an alternative compliance payment. The DPU is also developing a separate large-load rate structure aimed at preventing infrastructure costs associated with data centers from being shifted to other customers, while utilities are expected to introduce higher deposits, fees and other requirements to discourage speculative projects from entering the queue. If development accelerates across New England, these types of measures could become increasingly important given the region’s existing challenges around winter reliability, transmission and resource adequacy.
- CAISO is incorporating large-load growth into its existing transmission planning process and working with transmission owners on technical requirements for data center connections. Like other markets, one of the bigger challenges will be separating committed projects from speculative ones while making sure infrastructure development keeps pace with the load that materializes.
Despite the different approaches, the general direction is rather similar. Speed-to-power may increasingly depend on what the customer is willing to bring to the table, whether that is generation, flexibility, financial commitments or some combination of all three.
What Will Data Centers Actually Do?
There will not be one solid answer here.
The largest hyper-scalers have the financial resources to pursue long-term PPAs, support nuclear generation, contract with new gas plants, develop new renewable generation and storage, or participate in bringing new resources onto the grid.
Others may accept interruptible or non-firm service in exchange for quicker interconnection. Some may build on-site generation or storage. Others may locate projects in areas where generation and transmission are more readily available.
Location by itself may become a key part of the energy strategy.
A site with inexpensive land and good connectivity is far less attractive if it takes 7 to 10 years to obtain reliable power. Conversely, areas with available transmission, existing power plants or the ability to bring on new generators quickly may become more valuable to data center developers.
Why This Matters to Everyone Else
The large-load debate goes way beyond the technology industry because the decisions being made today will influence how billions of dollars in energy infrastructure are paid for.
Capacity is the most obvious example. If electricity demand grows faster than supply can be added, capacity prices will rise as the market tries to attract new supply.
Transmission is another. Large concentrations of new demand can require substations, poles and wires and significant network upgrades. If those investments are socialized across a utility territory or regional market, customers that had nothing to do with the original project could bear some of that cost.
Ancillary services could also become very important. Large loads capable of changing consumption quickly can create new operating issues, but that same flexibility could become an asset if data centers can reduce demand when needed.
The important issue is not simply how much electricity data centers use. It is how the rules determine who pays for the reliability and infrastructure costs created by that new consumption.
For decades, electricity consumers largely treated generation adequacy as someone else’s responsibility. Connect to the grid, buy electricity and let the utilities, generator owners and regional markets ensure the system had sufficient supply.
The AI boom is starting to change that relationship.
Data centers are arriving faster and at a greater scale than the grid has historically had to accommodate. FERC’s recent actions and the initiatives underway across the various markets point in the same general direction. New large loads may increasingly be expected to support new generation, accept some level of curtailment or flexible service, make firmer financial commitments, or take on a greater share of the infrastructure costs needed to serve them.
The particulars will vary from one market to another, and many of these rules are still very fluid. But the underlying questions are becoming a bit clearer, including how quickly new large loads should be allowed to connect, what they should be required to provide in return, and how much of the resulting costs should be borne by existing electricity consumers.
Getting these rules right could allow data center development to more forward while protecting grid reliability and existing customers. Getting them wrong could mean higher costs, an inadequate grid, or both.
That makes Bring Your Own Capacity much more than a data center story. It is rapidly becoming one of the defining questions determining how the next era of the U.S. electric grid is built and who pays for it.
About Stanwich Energy
Stanwich Energy is a trusted, independent energy advisory firm dedicated to helping organizations across the U.S. buy and manage energy more strategically. We provide energy procurement, sustainability solutions, risk management, reporting, and ongoing market intelligence supported by deep industry expertise and proprietary technology. Our client-first approach helps businesses reduce costs, optimize energy usage, and confidently navigate the complexities of today’s energy markets.
Ready to talk energy strategy? Share a few details on our Contact Us page and we’ll reach out to schedule a quick call.